Retail rents rise 0.7% in 3Q2026 despite second straight quarter of negative demand
The divergence signals demand concentrated in prime, well-managed malls rather than broad recovery, potentially supporting modest rental growth while encouraging weaker properties to rationalise or convert space.
The Central Region retail rental index rose 0.7% q-o-q to 81.2 in 3Q2026 despite occupied retail space contracting for a second consecutive quarter.
Body
The Urban Redevelopment Authority's (URA) retail rental index for the Central Region rose 0.7% q-o-q to 81.2 in 3Q2026, up from 0.6% in the preceding quarter, despite continued store closures and cautious retailer expansion.
The rental growth came even as occupied retail space contracted for the second consecutive quarter.
Rental growth was likely driven by Tier 1 shopping malls, which continue to attract strong retailer interest, rather than a broad-based improvement across the retail market, says Wong Xian Yang, Cushman & Wakefield's (C&W) head of research for Singapore and Southeast Asia.
JLL similarly notes that well-located malls with carefully curated tenant mixes and proactive asset management generally outperformed during the quarter, benefiting from stronger occupier demand.
Read also: Causeway Point AEI to introduce new social and reading hub with pre-loved books, Sing Lit
Despite challenging operating conditions, Singapore continues to attract new international retailers, particularly along Orchard Road, says Wong.
He points to recent openings by Korean footwear brand Rockfish Weatherwear at ION Orchard and London streetwear label Palace Skateboards at Scotts Square. Thai fashion label Gentlewoman also opened its first Singapore store at 313@Somerset in October.
Another upcoming entrant is Japanese doughnut chain I'm donut?, which is scheduled to open at ION Orchard in December.
CBRE also highlights expansion demand from F&B and fashion brands such as Chick-fil-A, Loulouca, Pop Bakery, In Good Company and Polène.
Despite widely reported retail and F&B closures, net business formation in the two sectors remained positive, at 992 entities as at August 2026, C&W's Wong notes.
At the same time, the retail landscape is transforming, with some established operators exiting or reducing their footprint and landlords exploring alternative uses for existing retail space.
Read also: Leasing kicks off at One Comcentre office and retail hub, with 1ha elevated park in heart of Orchard
Tricia Song, CBRE's head of research for Singapore and Southeast Asia, points to tenant exits and space rationalisation by operators such as True Fitness, Crystal Jade and Japan Home.
Against this backdrop, landlords are increasingly exploring alternative uses for retail space. Song highlights the repositioning of the former Taste Orchard at Orchard Point into JustCo Place.
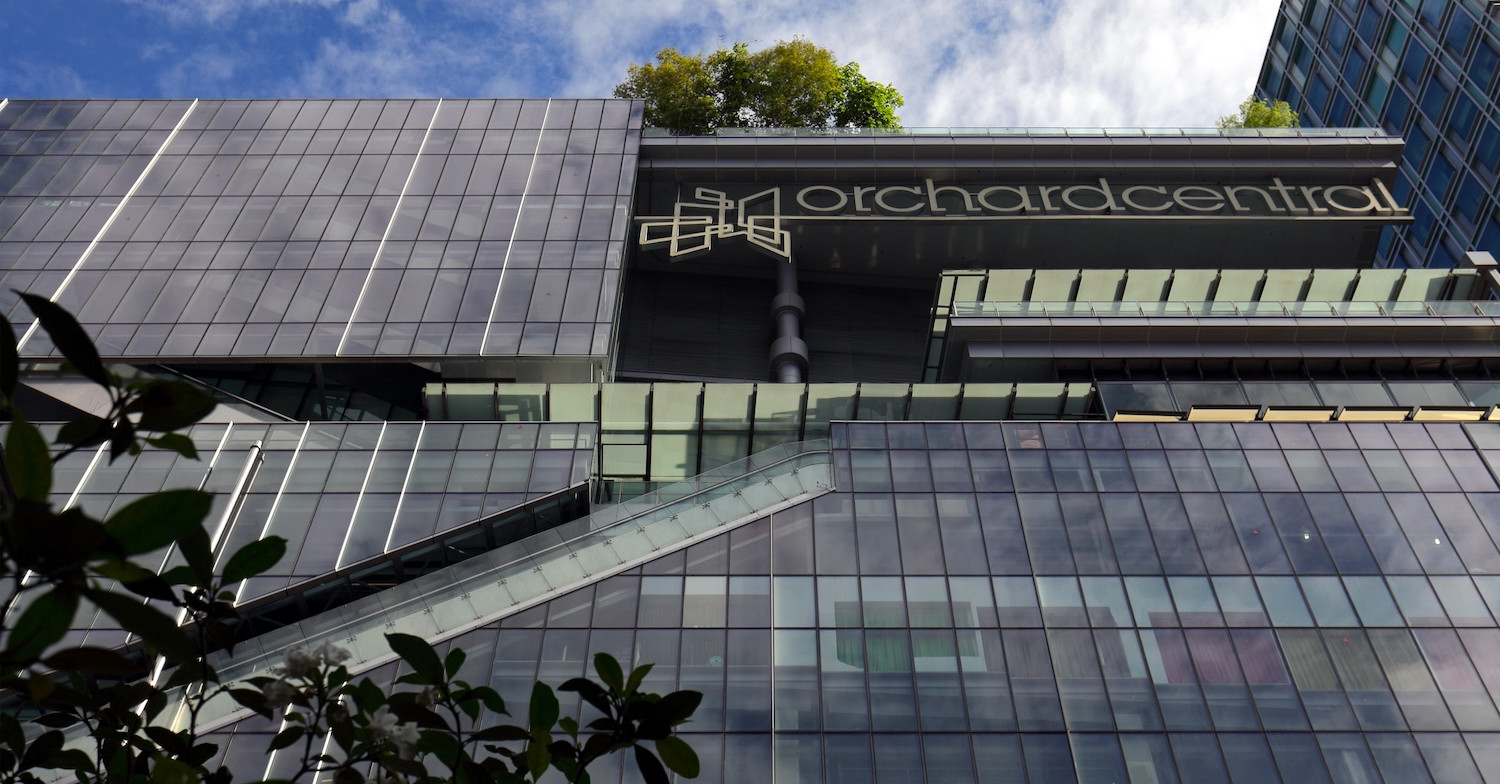
Meanwhile, Far East Organization announced in July that it was converting retail space on the upper floors of Orchard Central into offices, with renovation works scheduled to begin on Dec 1.
Song considers these developments the most significant retail-to-office shifts since The Centrepoint leased space to JustCo in 2020.
Across the island, occupied private retail space contracted by 21,000 sq m (226,044 sq ft) in 3Q2026, after a 29,000 sq m (312,156 sq ft) decline the previous quarter, according to CBRE.
Islandwide private retail vacancy remained unchanged at 7%, as the withdrawal of 22,000 sq m (236,808 sq ft) of existing retail stock, mainly due to the closure of HarbourFront Centre for redevelopment, largely offset the decline in occupied space, says CBRE.
Read also: Tourism board invites proposals to redevelop Emerald Hill site into hotel, lifestyle destination
According to CBRE, the Outside Central Region (OCR) was the only submarket in its breakdown to record positive net absorption in 3Q2026, with occupied space increasing by 6,000 sq m (64,584 sq ft), after declining by 12,000 sq m (129,168 sq ft) in the preceding quarter.
Consequently, vacancy in the OCR fell to 4.7% from 5.2% in 2Q2026, reflecting continued retailer interest in suburban locations with resilient residential catchments.
Looking ahead, retail supply is expected to remain relatively limited. URA data shows that about 35,000 sq m (376,740 sq ft) of gross retail space is scheduled for completion in 2027, rising to 103,000 sq m (1.11 million sq ft) in 2028.
C&W's Wong estimates that only 4% of upcoming retail supply between 2027 and 2031 will be located along Orchard Road, suggesting that supply pressures in Singapore's prime shopping belt will remain limited.
Nevertheless, retailers continue to face challenges from rising operating costs, manpower shortages and intense e-commerce competition.
JLL expects rental growth to remain modest as retailers adopt a cautious approach to expansion. CBRE's Song forecasts prime retail rents to rise 1% to 2% for all of 2026.