Buyers snap up new Hong Kong flats ahead of likely interest rate rises
The sell-out signals buyers are accelerating purchases before possible mortgage-rate increases, potentially encouraging developers to advance discounted launches while current transaction sentiment remains supportive.
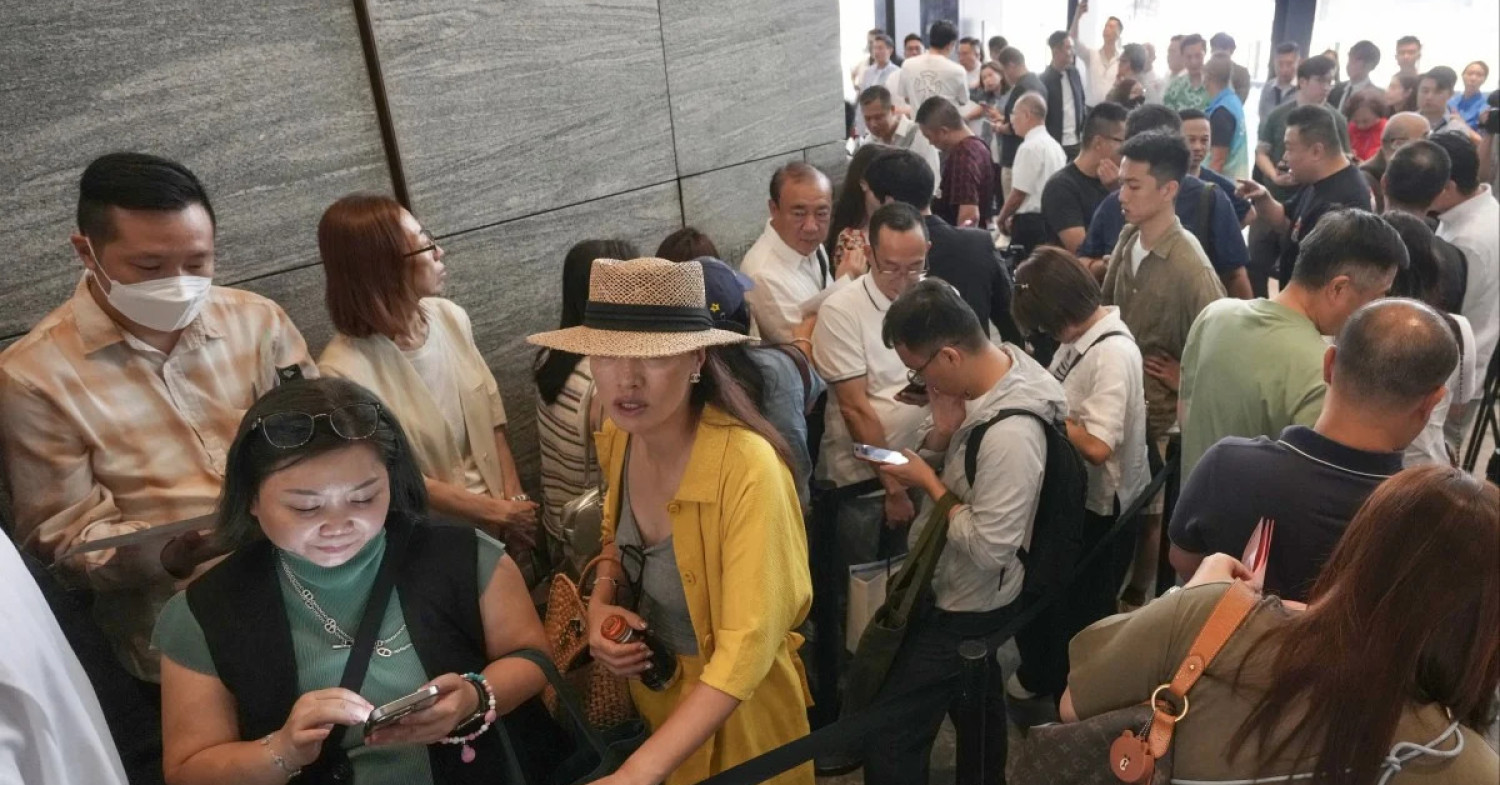
Hong Kong developers sold all more than 290 new flats launched over Sept 26–27, including 140 State Residence units and 153 The Sterling II units.
Body
Hong Kong developers sold all of the more than 290 new flats they launched over the weekend of Sept 26–27, as buyers looked to lock in mortgages ahead of an anticipated rise in interest rates later this year, according to property agents.
The decision by the city’s major banks to hold rates steady despite the US Federal Reserve’s recent rate increase appeared to have given buyers a push, with many expecting local rates to rise in the coming months, said Derek Chan Hoi-chiu, head of research at Ricacorp Properties.
“A notable number of home seekers are actively entering the market to secure properties ahead of anticipated local rate increases,” Chan said.
Read also: Hong Kong converts hotels into student dorms
On Sept 26, Chow Tai Fook-owned Sky Ace Enterprises shifted all of the 140 apartments it made available on its State Residence project in North Point, agents said.
The properties are a mix of one-bedroom to three-bedroom flats with between 28 sq m (301 sq ft) and 56 sq m (603 sq ft) of floor space. They were offered at discounted prices starting from HK$5.96 million ($970,800).
China Land Resources, meanwhile, found buyers for all 153 apartments at The Sterling II made available on Sept 27, agents said. The flats — ranging from 28.5 sq m (307 sq ft) to 67.8 sq m (730 sq ft) — were also offered at discounted prices of HK$5.43 million to HK$15.01 million.
The southwest Kowloon project also offered 35 flats via tender starting Sept 27.
“Developers are likely to push out launches quicker to avoid interest hike uncertainty,” said Norry Lee, senior director of projects strategy and consultancy at JLL in Hong Kong.
The latest sales performance is likely to provide some relief to the property market, after Hong Kong’s lived-in home prices fell 0.46% in July, halting a 13-month upswing, according to the latest official data.
The index tracking second-hand home prices slipped to 321.5 in July from 323 in June, the first decline recorded in 16 months, Rating and Valuation Department data showed.
Read also: Foreign, mainland students flock to Hong Kong, sparking property demand in education sector
The decline came weeks before the recent interest rate increase.
On Sept 17, the Hong Kong Monetary Authority lifted the city’s base rate to 4.25% after the US Federal Reserve had raised its target range to between 3.75% and 4% following its latest Federal Open Market Committee meeting.
The city’s three note-issuing banks did not follow suit. HSBC and Bank of China (Hong Kong) kept their prime lending rate at 5%, while Standard Chartered maintained its prime rate at 5.25%, according to separate statements from the lenders.
The Fed is set to meet again in late October. If it raises its target rate again, that could finally trigger Hong Kong’s lenders to adjust their own rates, analysts said.
“Despite potential upside risks in US interest rates and the likelihood of Hong Kong following suit, prevailing market optimism continues to support transaction activity,” Chan of Ricacorp said.
The timing of the launches also had a positive impact on the sales, according to Lee of JLL.
“Timing matters: with Mid-Autumn Festival this week and the National Day ‘golden week’ next week, developers are keen to catch this window for mainland buyers,” he said.
Read also: Super-rich losing millions as some Hong Kong trophy homes sell at painful discounts