Private home prices rise 1.4% despite weakest 3Q new-home sales since 1998: URA flash estimates
The divergence signals price growth driven by fewer launches and a greater share of higher-value transactions, while upcoming supply and higher interest rates may shape demand.
Private home prices rose 1.4% in 3Q2026 despite new-home sales falling to about 1,100 units, the weakest third-quarter volume since 1998.
Body
URA's flash estimates showed private home prices rose 1.4% in 3Q2026, up from 0.5% the previous quarter.
It marked the eighth consecutive quarter of price gains and the fastest quarterly increase in almost two years, says Christine Sun, chief researcher and strategist at Realion (OrangeTee & ETC) Group. The last time prices rose faster was in 4Q2024, when they increased 2.3%.
“Overall, prices grew faster due to a bigger proportion of private homes sold at a higher price,” says Sun.
Search for the latest New Launches, to find out the transaction prices and available units
For instance, the proportion of private homes, excluding executive condominiums (ECs), sold for at least $2 million rose from 49.2% in 2Q2026 to 53.6% in 3Q2026, according to Realion.
The shift was even more pronounced in the new sale market, where the share of transactions of at least $2 million surged from 52.3% to 71.7% over the same period, Sun notes.
Private home prices have risen 2.8% in the first nine months of 2026.
Landed homes, OCR lead price gains
The main driver of the price increase in 3Q2026 was the landed housing segment, where prices rose 2.8%, following a 2.5% increase in 2Q2026.
Non-landed home prices increased 0.9%, reversing the 0.1% decline in the preceding quarter.
Among the three market segments, the Outside Central Region (OCR) recorded the strongest price growth at 2.2%, reversing a 0.1% decline in 2Q2026. Huttons Asia attributes the increase partly to higher price benchmarks set by projects such as Vela Bay.
Prices in the Rest of Central Region (RCR) edged up 0.2%, following a 1.2% decline in the previous quarter.
Meanwhile, Core Central Region (CCR) prices slipped 0.1%, reversing the 1.8% growth recorded in 2Q2026.
Read also: Amberwood at Holland sells 11% of units on launch weekend, averaging $3,019 psf
URA private property price index for 2Q2026 vs 3Q2026
Launches and sales fell sharply in 3Q2026
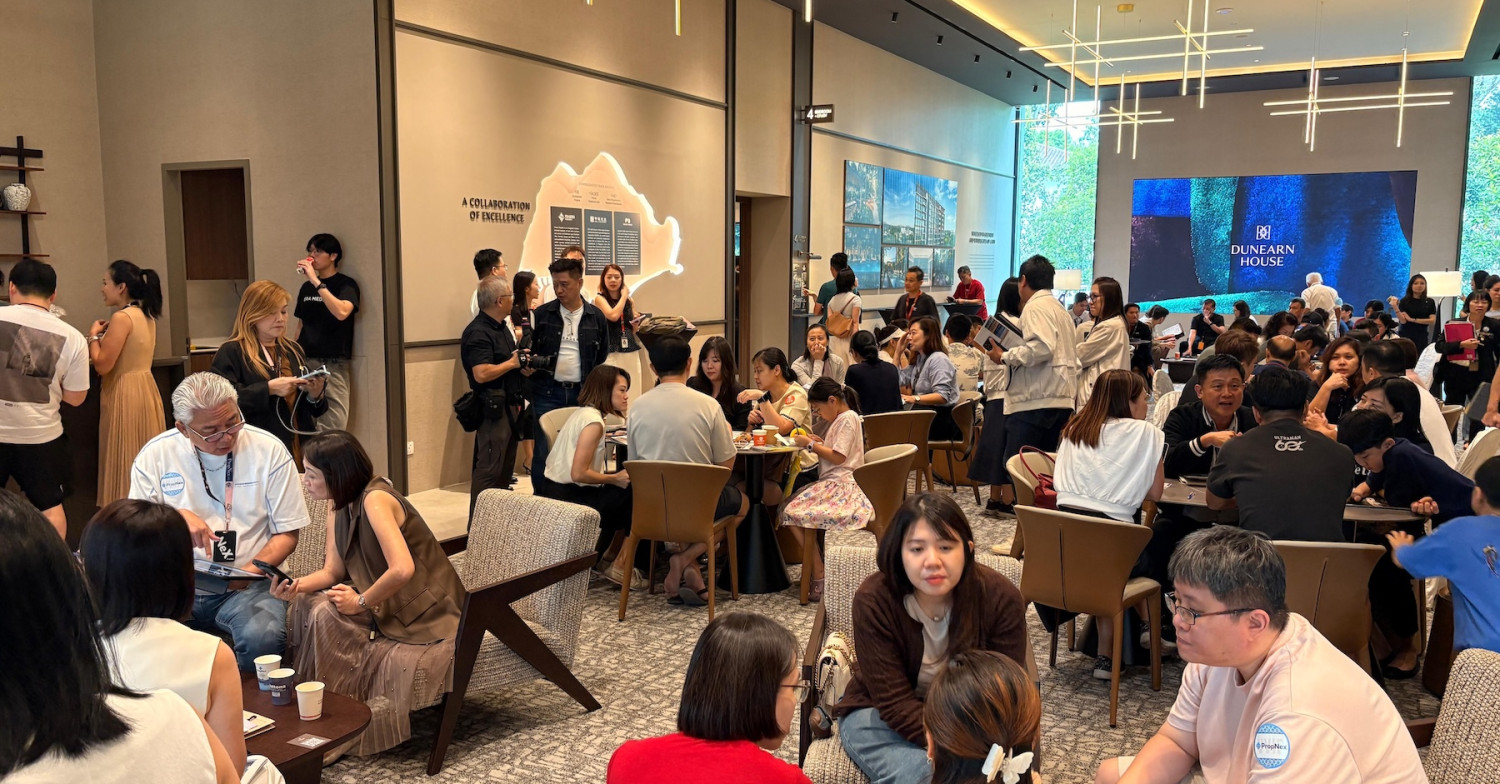
Major condominium projects launched during the quarter included the 212-unit Amberwood at Holland, 380-unit Dunearn House and 499-unit Lentor Gardens Residences.
Two boutique projects, the 20-unit Duet @ Emily on Mount Emily and the 27-unit The Bronze on Boon Teck Road, were also launched during the quarter, according to SRI.
Launch activity was constrained by the Lunar Seventh Month, says Huttons. An estimated 1,100 units were launched for sale in 3Q2026, 38.3% fewer than in the previous quarter and 73.8% lower than a year ago. According to Huttons, this was the lowest number of units launched in a third quarter.
The limited supply of new launches also weighed on developers' sales. Based on Huttons Data Analytics estimates, about 1,100 new homes were sold in 3Q2026, down 48.6% q-o-q and 66.4% y-o-y.
As developers' sales are supply-led, fewer launches led to correspondingly lower transaction volumes, says Mark Yip, CEO of Huttons Asia.
He adds that uncertainty surrounding the US-Iran truce also prompted some buyers to delay their purchases while awaiting greater clarity. The estimated 1,100 new homes sold made 3Q2026 “the lowest number of units sold in the third quarter of the year since 1998”, according to Yip.
Read also: Sim Lian Group to preview Amberwood at Holland on Sept 11, with prices starting from $2,921 psf
Sales down 46.6% in first nine months
In the first nine months of 2026, developers launched an estimated 4,727 units, 46.6% fewer than in the same period last year. An estimated 5,254 units were sold over the same period, down 33.3% year on year.
Huttons estimates private housing demand in the OCR fell 39.2%, partly due to affordability concerns. Demand in the RCR fell 26.3%, while demand in the CCR rose 1.2%.
Across the primary and secondary markets, sales volume totalled about 4,300 units in 3Q2026, down 30% from 6,148 units in the previous quarter.
Huttons says some buyers also paused their purchases as they digested several recent policy changes affecting the housing market, including the removal of the 15-month wait-out period and changes to the Primary 1 Phase 2C allocation framework from 2027.
More launches expected in 4Q2026
Activity could rebound sharply in the final quarter, when several large projects are scheduled for launch.
[object Object]
“The final quarter of 2026 will likely see a noticeable surge in transactions due to the highly anticipated line-up of blockbuster launches,” says Sun.
These include the 570-unit Lucerne Grand, the 1,268-unit Thomson Reserve and the 133-unit The Serra, which will collectively introduce about 2,000 new private homes.
Sun says the 1,268-unit Thomson Reserve could also influence the overall private residential price index in 4Q2026. Located in the RCR, the project is expected to be priced above $2,600 psf.
“The massive volume and premium city-fringe pricing from this project alone may lead to an uplift in the overall private property price index in 4Q2026,” she says.
However, higher interest rates could temper demand. In September, the US Federal Reserve raised its benchmark interest rate by 25 basis points to a target range of 3.75% to 4%, its first increase since July 2023.
“Nevertheless, some buyers may exercise caution as interest rates could continue to rise in the months ahead,” says Sun.
Labour risks, generational wealth
Domestic economic conditions are another risk. Knight Frank Singapore head of research Leonard Tay says “an eye needs to be kept on the labour market”.
While unemployment remains low, retrenchments increased from 3,830 in 1Q2026 to 4,620 in 2Q2026, with layoffs concentrated in sectors such as manufacturing, information and communications, and financial services.
“There is a sense of uncertainty creeping into the labour market with the proliferation of AI-related disruptors in several industries,” says Tay. “Should job security be undermined, prospective homebuyers might hold off on making a purchase and adopt a more cautious wait-and-see posture.”
At the same time, intergenerational transfers of housing wealth are creating another source of demand in the residential market, says Marcus Chu, CEO of ERA Singapore.“We are seeing older homeowners right-size and unlock equity from properties that have appreciated significantly, while some younger buyers receive family support for their first or next home,” he notes.
“It also helps explain why purchasing power has remained relatively resilient even as home prices and affordability pressures have increased.”
For the full year, SRI head of research and data analytics Mohan Sandrasegeran expects private residential prices to increase by about 3% to 3.5% in 2026, broadly in line with the 3.3% increase recorded in 2025.
“We expect price growth to remain relatively measured in the final quarter,” says Sandrasegeran. “A broader pipeline of new launches in 4Q2026 should provide homebuyers with greater choice across different locations and price points.”
Check out the latest listings for Amberwood At Holland, Dunearn House, Lentor Gardens Residences properties