Vietnam leads Apac branded residences market by number of units, ranks third globally
Vietnam’s 49-project pipeline and Asia Pacific’s 36% annual pipeline growth signal robust developer confidence, potentially increasing branded-residence supply and competition across regional markets.
Vietnam leads Asia Pacific with 16,135 branded residences across 68 completed and pipeline developments, ranking third globally behind the UAE and US.
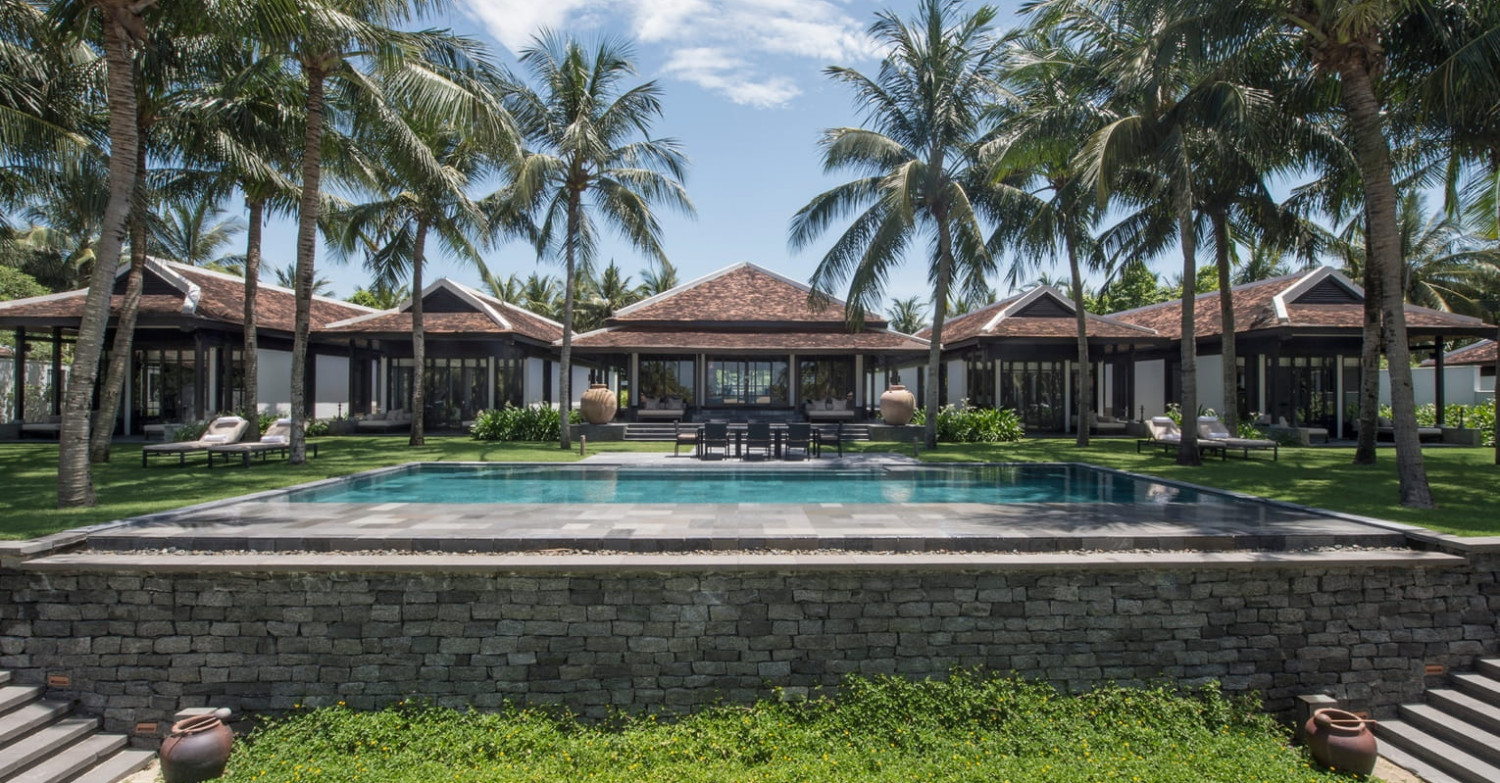
Body
Vietnam has topped the Asia Pacific (Apac) branded residences market by number of units, with 16,135 residences across 68 completed and pipeline developments.
This makes it the third largest in the world, behind the United Arab Emirates (84,972 units) and the US (71,592 units), according to Global Branded Residences, a UK-based advisory firm that specialises in the market.
The data, compiled in The Brand Standard, the firm’s inaugural annual report, shows that Vietnam has the highest number of branded residential units in Apac despite having fewer developments compared to Thailand, which ranked second. The runner-up has 14,141 branded residences across 73 completed and pipeline projects.
Read also: Apac data centre capacity to double by 2030, AI boom creating 'generational shift' in power demand: JLL
India ranked third for both, with 13,908 residences across 61 developments.
Riyan Itani, founder of Global Branded Residences, notes that while the sector is “usually” measured by the number of developments, looking at the number of units offers further insight. “Counting the residences inside those developments tells you how much product is actually coming to market and how significant the buyer demand actually is.”
In any case, the Apac branded residences market continues to grow, backed by a sizeable pipeline. According to the report, the number of pipeline schemes has surged 36% over the past 12 months, going from 147 projects to 200.
Combined with its 198 completed developments, the region has a total of 398 schemes. It accounts for 20% of global branded residences stock, after North America (452 projects or 23%) and the Middle East and North Africa (Mena) (426 projects or 22%).
Vietnam, Thailand drive growth
Vietnam is currently the biggest contributor to Apac’s pipeline, with 49 projects located across cities such as Hanoi and Ho Chi Minh City as well as coastal destinations including Da Nang, Phu Quoc, Hoi An and Ha Long. These include Mercure Residences Ha Long, a 2,259-unit scheme that is the single-largest branded residential development in Apac.
The pipeline is the sixth-largest for a country globally, following the UAE, the US, Mexico, Brazil and Saudi Arabia. Vietnam has completed 19 projects to date.
Thailand is the region’s next-biggest driver, with 37 pipeline developments and 36 completed ones. With 73 projects overall, Thailand is the fifth-biggest market among standalone countries by number of schemes. It is also the third largest for completed stock.
Read also: JLL appoints Mikhail Jaura as Apac head of data centre research
A key market within the country is Phuket, with Global Branded Residences estimating 19 pipeline developments on the Thai island, on top of 13 completed projects. In terms of standalone cities, Phuket is the fifth-largest market in the world by overall developments, behind Dubai, Miami, São Paulo and New York.
All but one of Phuket’s 32 total schemes are in resort locations. This makes it the “largest resort branded residences market in the world”, competing in scale with major capital and gateway cities. “That tells us branded residences are increasingly following international buyers into destinations where lifestyle and leisure are fundamental to the purchasing decision,” adds Itani.
Broader market
The report also highlights that Apac offers a broader spectrum of offerings that reach a wider base in contrast to the North America, Mena and Europe markets. “It has a much wider spread of price points, a strong regional brand ecosystem and an increasingly resort-led pipeline,” says Itani.
Luxury projects account for 61% of Apac’s schemes, compared to 76% for North America. In addition, the region accounts for 54%, 35% and 33% of the midscale, upper-midscale and upscale schemes globally, despite making up less than a quarter of overall stock.
Apac branded residences are also able to command a slightly higher premium versus equivalent non-branded residences. According to the report, Apac schemes have an average price premium of 47%, compared to the global average of 44%.
The premium may reflect the dominance of hotel brands in the region, along with the significance of its resort destinations.
Read also: Investors to deploy more capital to Apac living sector over next five years: C&W
Hotel brands account for 78% of Apac’s overall branded residence schemes, and 82% of pipeline projects. Meanwhile, some 93% of Apac’s resort schemes carry a hotel brand.
Nonetheless, Apac remains the only region worldwide that is not led by Marriott or Accor. The two hospitality giants dominate branded residences elsewhere, making up more than a quarter of overall developments globally.
However, in Apac, Banyan Group leads with around 50 projects, surpassing Accor at 44 and Marriott at 34.